The Free Phone Is a Loan in Disguise: What 2026 Carrier Promotions Actually Cost
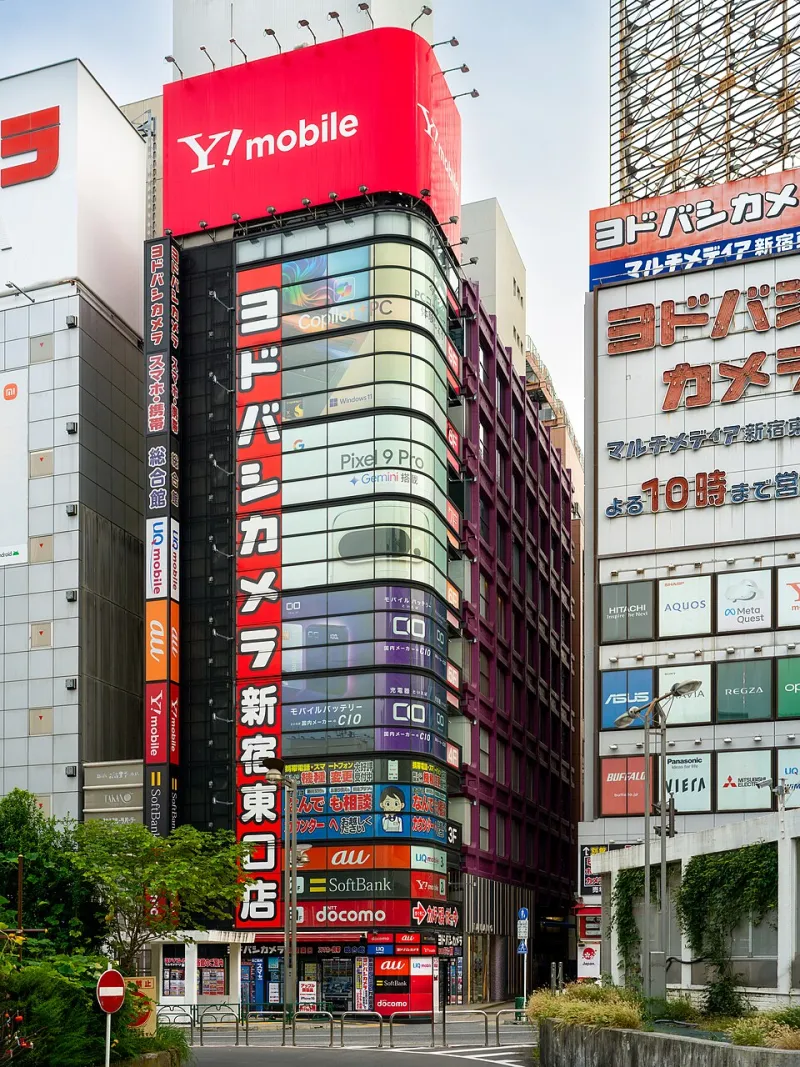
Photo: Dale Cruse from San Francisco, CA, USA, CC BY 2.0, via Wikimedia Commons
Walk into any US carrier store this fall and the signage still promises a free phone. Read the tag beneath the headline and the offer becomes something else entirely: a thirty-six-month installment agreement, a monthly bill credit that only arrives if you stay, a trade-in that must survive inspection, and an unlock policy that decides whether the device is ever truly yours.
None of that is illegal, and none of it is new in kind. What has changed in 2026 is the arithmetic. Promotional credits now stretch across three-year terms more often than two, trade-in valuations have grown more conditional, and the gap between the advertised price and the financed price has widened enough that the word free deserves a footnote.
This is an analysis of how the deals are built, not a verdict on any single carrier. The structures below are common across the industry; specific terms vary by promotion and change frequently.
How a bill credit actually works
A carrier promotion typically operates in three steps. You agree to a retail installment contract for the full device price. The carrier issues a monthly credit against your service bill, sized so that the credits total roughly the device cost over the term. You receive the credit only while you remain on an eligible plan.
Functionally, the carrier has extended you an interest-free loan and is paying it down on your behalf, contingent on your continued business. That is a reasonable trade for both sides — carriers get retention, you get hardware — but it is a loan, and it should be evaluated like one.
Three consequences follow from that structure:
- Early exit is expensive. Leave before the term ends and the remaining balance typically comes due, minus credits you will not receive.
- The credit is not cash. It cannot be applied to accessories, taxes, or a different device.
- Plan requirements carry their own cost. Promotions are usually tied to premium unlimited plans. The difference between a promotional plan and a cheaper one can exceed the value of the credit over three years.
A representative comparison
Numbers vary widely, so treat the following as an illustration of method rather than a quote. Consider a flagship phone with a $1,000 retail price.
| Path | Upfront | Monthly | 36-month total | Notes |
|---|---|---|---|---|
| Carrier promo, qualified trade-in | $0 device cost | ~$0 device + plan premium | Device effectively covered; plan may cost $15–$25/mo more than a budget tier | Credit forfeited if you leave early |
| Carrier promo, no trade-in | $0 | ~$27.78 | ~$1,000 financed | Full price, no discount, same lock-in |
| Unlocked, bought outright | ~$1,000 | $0 | ~$1,000 | Portable across carriers; resale value retained |
| Unlocked, mid-range alternative | ~$500 | $0 | ~$500 | Sufficient for most users |
The promo column looks best only when the trade-in qualifies and the plan premium is genuinely one you would have paid anyway. If either condition fails, the math inverts quickly.
Where the fine print bites
Trade-in condition grading. Devices are assessed after receipt, not in the store. A cracked rear panel, a failing battery, or a screen replaced by a third-party shop can downgrade an estimate, and the adjustment usually appears as a reduced monthly credit rather than a clear bill line. Photograph the device and note its condition before shipping.
Promotional plan tiers. Confirm the exact plan name in writing and check whether a cheaper tier is excluded. Ask what happens if the carrier discontinues that plan mid-term — the answer is often that you must migrate to an eligible plan or lose remaining credits.
Unlock timing. Devices are typically locked until the installment agreement is satisfied, with additional waiting periods in some cases. That matters if you travel internationally with a local SIM, sell the phone, or simply want the option to switch.
Line and account requirements. Many offers require a new line, a port-in, or a specific account type. Adding a line you do not need to capture a discount is a common and costly mistake.
Auto-pay and paperless discounts. The quoted monthly price often assumes both. Drop either and the bill rises.
When the promo is genuinely the right call
There are real winners here. If you were going to buy that exact flagship anyway, stay on that plan tier for three years regardless, and have a trade-in device sitting in a drawer, the promotional route can beat buying unlocked by several hundred dollars. The structure rewards stability, and stable customers should take the discount.
Everyone else should run three questions before signing. First, what is the total cost of the plan over the full term compared with the cheapest plan that meets my needs? Second, would I still want this device in three years? Third, what happens to the balance if my circumstances change?
If any answer is uncomfortable, an unlocked device bought outright — or a certified refurbished unit — usually wins. You give up the subsidy and keep the exit.
The free phone never disappeared. It just stopped being free the moment the term, the trade-in, and the unlock policy were added to the price tag.